
ResMed currently trades at $218.94 per share and has shown little upside over the past six months, posting a small loss of 2.7%. The stock also fell short of the S&P 500’s 15.9% gain during that period.
Is now the time to buy RMD? Or does the price properly account for its business quality and fundamentals? Find out in our full research report, it’s free.
Why Does ResMed Spark Debate?
Founded in 1989 to address the then-underdiagnosed condition of sleep apnea, ResMed (NYSE:RMD) develops cloud-connected medical devices and software solutions that treat sleep apnea, COPD, and other respiratory disorders for home and clinical use.
Two Positive Attributes:
1. Constant Currency Revenue Drives Growth
Investors interested in Patient Monitoring companies should track constant currency revenue in addition to reported revenue. This metric excludes currency movements, which are outside of ResMed’s control and are not indicative of underlying demand.
Over the last two years, ResMed’s constant currency revenue averaged 8.9% year-on-year growth. This performance was solid and shows it can expand steadily on a global scale regardless of the macroeconomic environment. 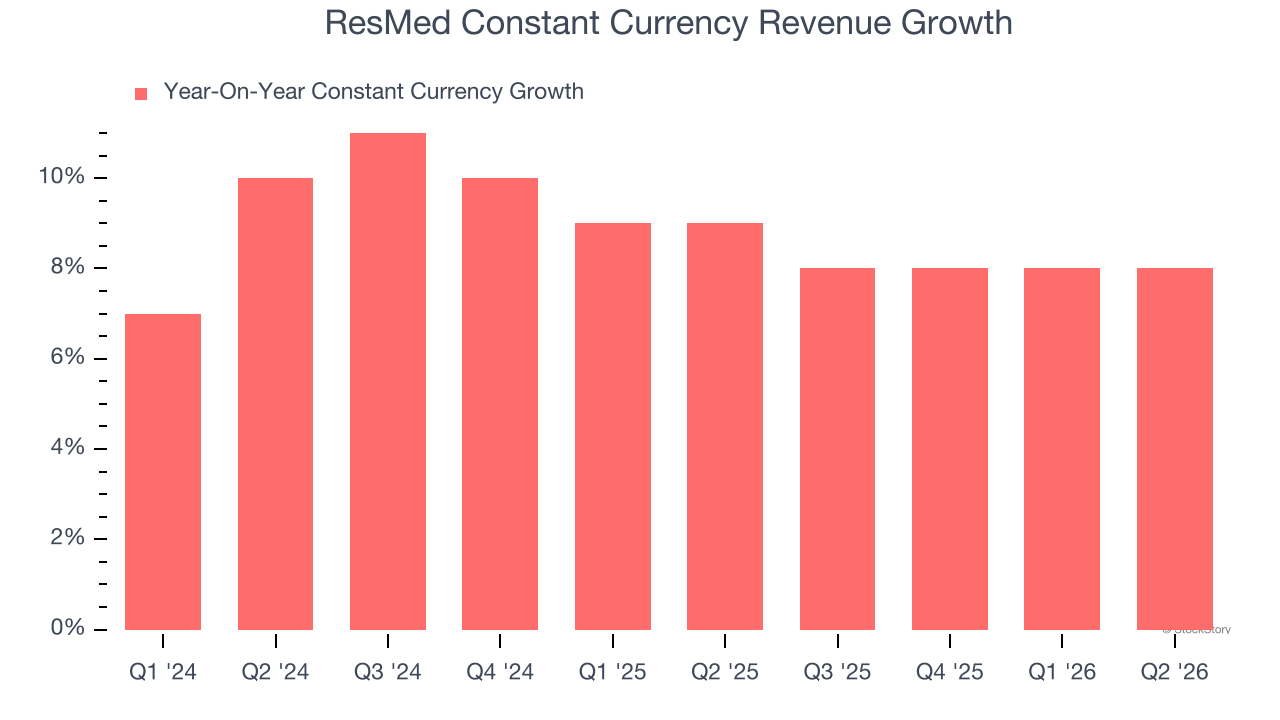
2. Increasing Free Cash Flow Margin Juices Financials
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
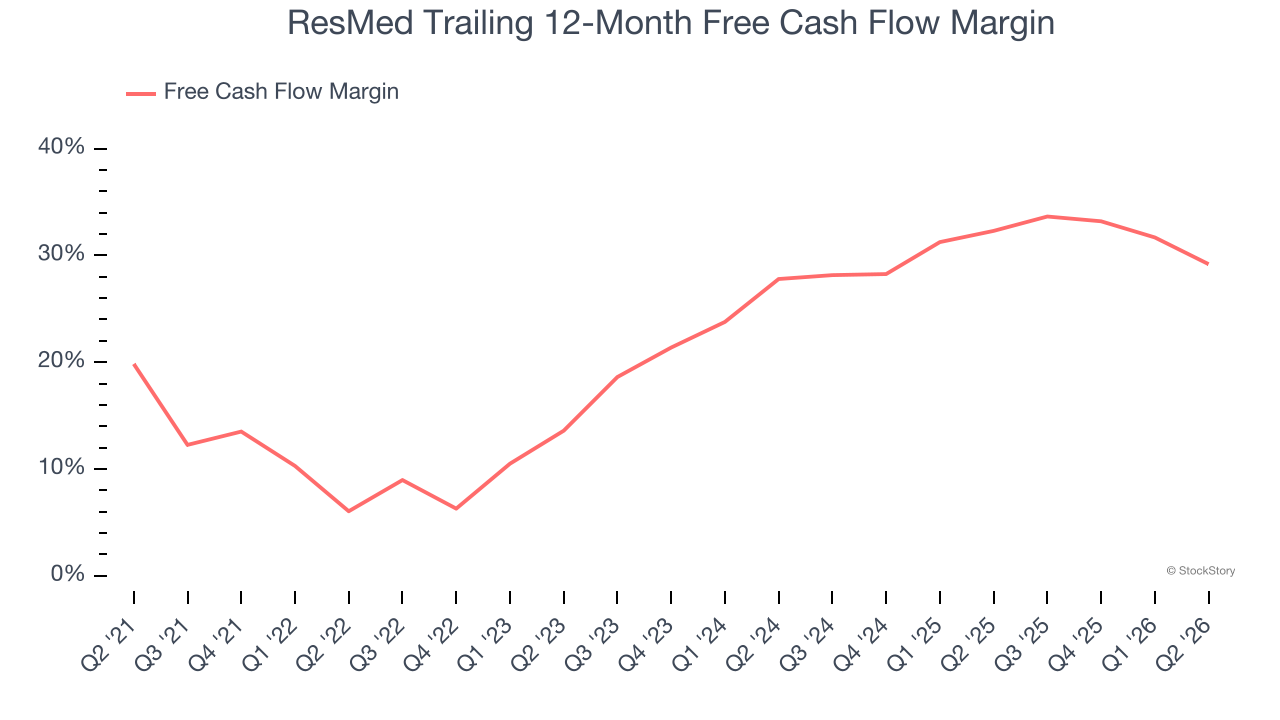
As you can see below, ResMed’s margin expanded by 23.1 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. ResMed’s free cash flow margin for the trailing 12 months was 29.2%.
One Reason to Be Careful:
Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect ResMed’s revenue to rise by 2.7%, a deceleration versus its 12.1% annualized growth for the past five years. This projection is underwhelming and indicates its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
Final Judgment
ResMed’s merits more than compensate for its flaws. With its shares underperforming the market lately, the stock trades at 18.2× forward P/E (or $218.94 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.