

As the Q2 earnings season wraps, let’s dig into this quarter’s best and worst performers in the beverages, alcohol, and tobacco industry, including Constellation Brands (NYSE:STZ) and its peers.
These companies' performance is influenced by brand strength, marketing strategies, and shifts in consumer preferences. Changing consumption patterns are particularly relevant and can be seen in the rise of cannabis, craft beer, and vaping or the steady decline of soda and cigarettes. Companies that spend on innovation to meet consumers where they are with regards to trends can reap huge demand benefits while those who ignore trends can see stagnant volumes. Finally, with the advent of the social media, the cost of starting a brand from scratch is much lower, meaning that new entrants can chip away at the market shares of established players.
The 13 beverages, alcohol, and tobacco stocks we track reported a satisfactory Q2. As a group, revenues beat analysts’ consensus estimates by 1% while next quarter’s revenue guidance was 2.2% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 11.7% since the latest earnings results.
Constellation Brands (NYSE:STZ)
With a presence in more than 100 countries, Constellation Brands (NYSE:STZ) is a globally renowned producer and marketer of beer, wine, and spirits.
Constellation Brands reported revenues of $2.43 billion, down 3.3% year on year. This print exceeded analysts’ expectations by 1.6%. Overall, it was a satisfactory quarter for the company with an impressive beat of analysts’ organic revenue estimates but full-year revenue guidance slightly missing analysts’ expectations.
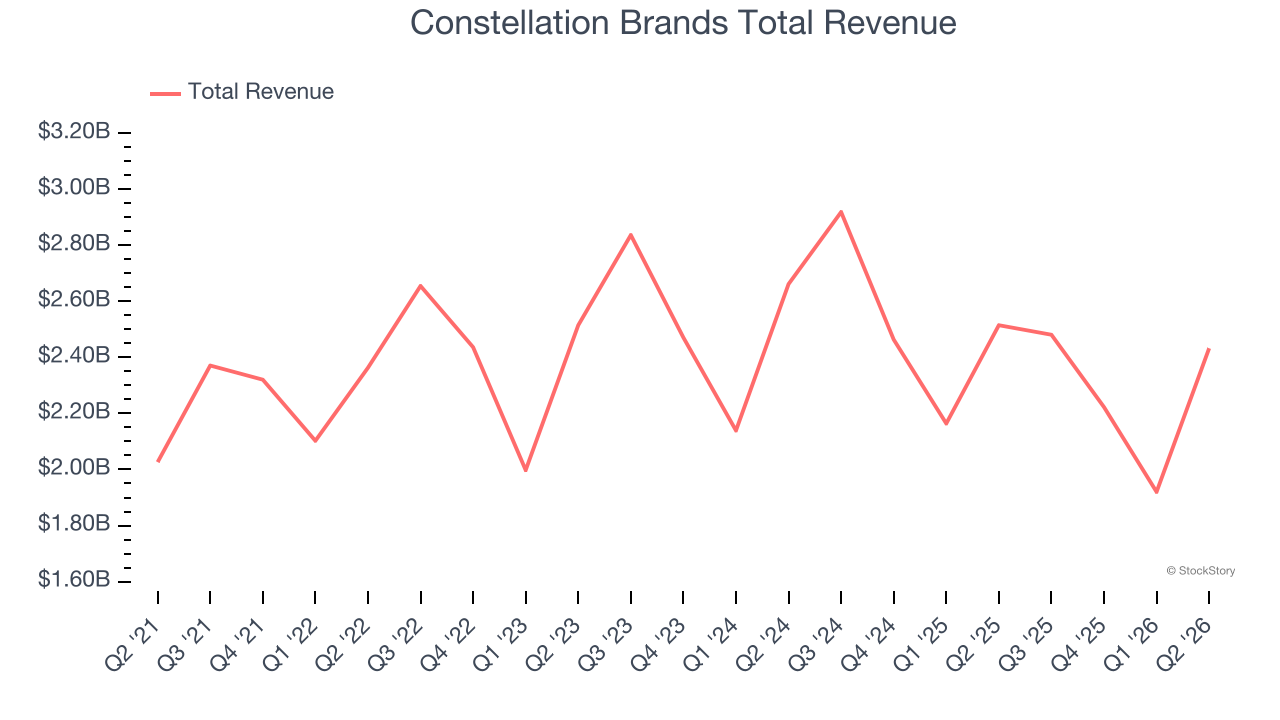
Constellation Brands delivered the weakest full-year guidance update among its peers. Even though it had a relatively good quarter, the market seems discontent with the results. The stock is down 18.7% since reporting and currently trades at $113.04.
Is now the time to buy Constellation Brands? Access our full analysis of the earnings results here, it’s free.
Best Q2: Vita Coco (NASDAQ:COCO)
Founded in 2004 followed by a 2021 IPO, The Vita Coco Company (NASDAQ:COCO) offers coconut water products that are a natural way to quench thirst.
Vita Coco reported revenues of $216.2 million, up 28.1% year on year, outperforming analysts’ expectations by 3%. The business had a stunning quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ gross margin estimates.
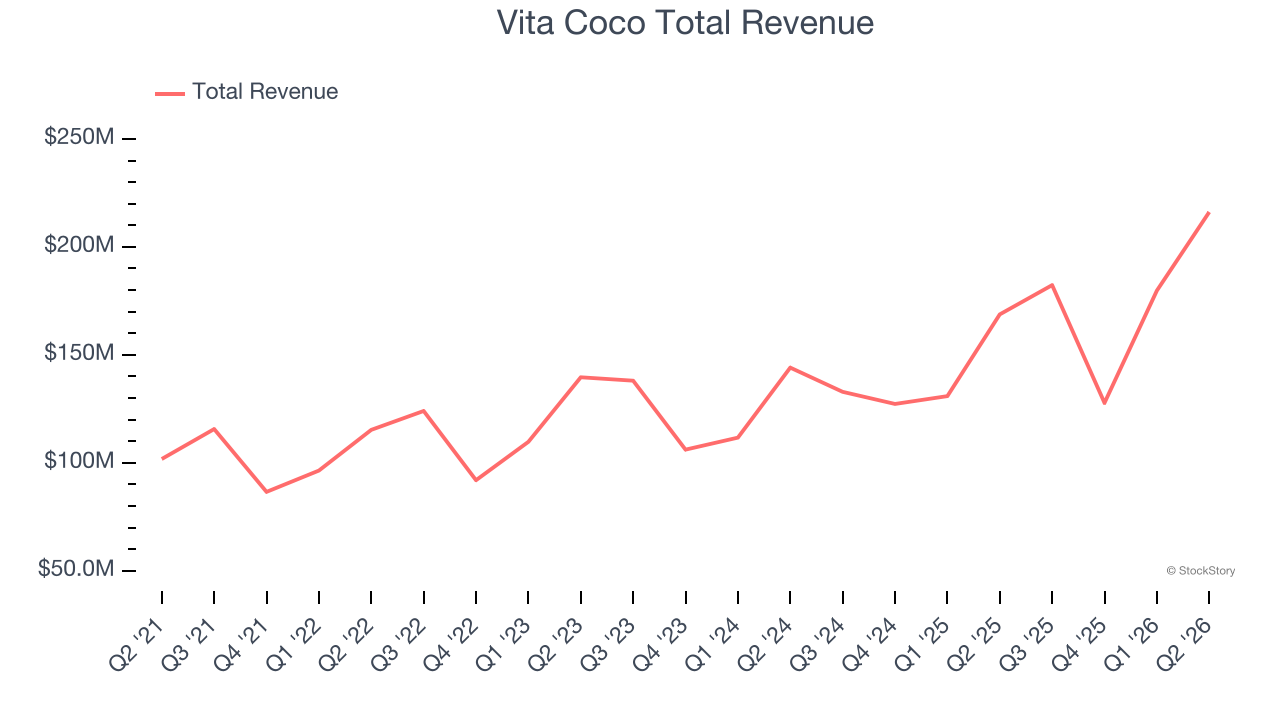
Vita Coco delivered the highest full-year guidance raise of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 23.2% since reporting. It currently trades at $57.16.
Is now the time to buy Vita Coco? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Celsius (NASDAQ:CELH)
With its proprietary MetaPlus formula as the basis for key products, Celsius (NASDAQ:CELH) offers energy drinks that feature natural ingredients to help in fitness and weight management.
Celsius reported revenues of $817.9 million, up 10.6% year on year, falling short of analysts’ expectations by 6.2%. It was a disappointing quarter as it posted a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
Celsius delivered the weakest performance against analyst estimates in the group. As expected, the stock is down 8.1% since the results and currently trades at $26.78.
Read our full analysis of Celsius’s results here.
Zevia (NYSE:ZVIA)
With a primary focus on soda but also a presence in energy drinks and teas, Zevia (NYSE:ZVIA) is a better-for-you beverage company.
Zevia reported revenues of $45 million, up 1.1% year on year. This print beat analysts’ expectations by 1.8%. It was a very strong quarter as it also logged EBITDA guidance for next quarter exceeding analysts’ expectations and an impressive beat of analysts’ EBITDA estimates.
The stock is down 29.5% since reporting and currently trades at $1.21.
Read our full, actionable report on Zevia here, it’s free.
Molson Coors (NYSE:TAP)
Sporting an impressive roster of iconic beer brands, Molson Coors (NYSE:TAP) is a global brewing giant with a rich history dating back more than two centuries.
Molson Coors reported revenues of $3.10 billion, down 3.3% year on year. This number met analysts’ expectations. Zooming out, it was a satisfactory quarter as it also produced a solid beat of analysts’ EBITDA estimates but a significant miss of analysts’ gross margin estimates.
The stock is down 11.5% since reporting and currently trades at $37.05.
Read our full, actionable report on Molson Coors here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.