
Over the past six months, Encore Capital Group has been a great trade, beating the S&P 500 by 16.3%. Its stock price has climbed to $95.89, representing a healthy 32.2% increase. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Encore Capital Group, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Encore Capital Group Not Exciting?
Despite the momentum, we don’t have much confidence in Encore Capital Group. Here are three reasons why ECPG doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
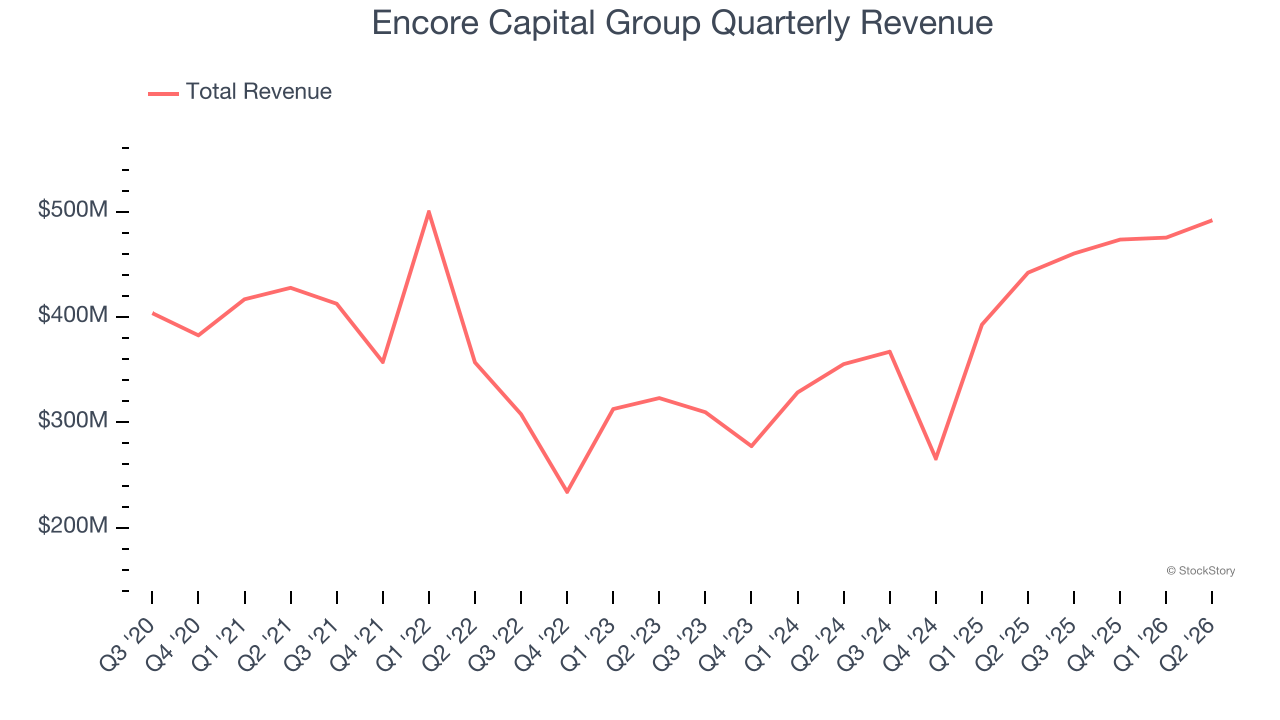
Over the last five years, Encore Capital Group grew its revenue at a sluggish 3.1% compounded annual growth rate. This fell short of our benchmark for the financials sector.
2. Previous Growth Initiatives Haven’t Impressed
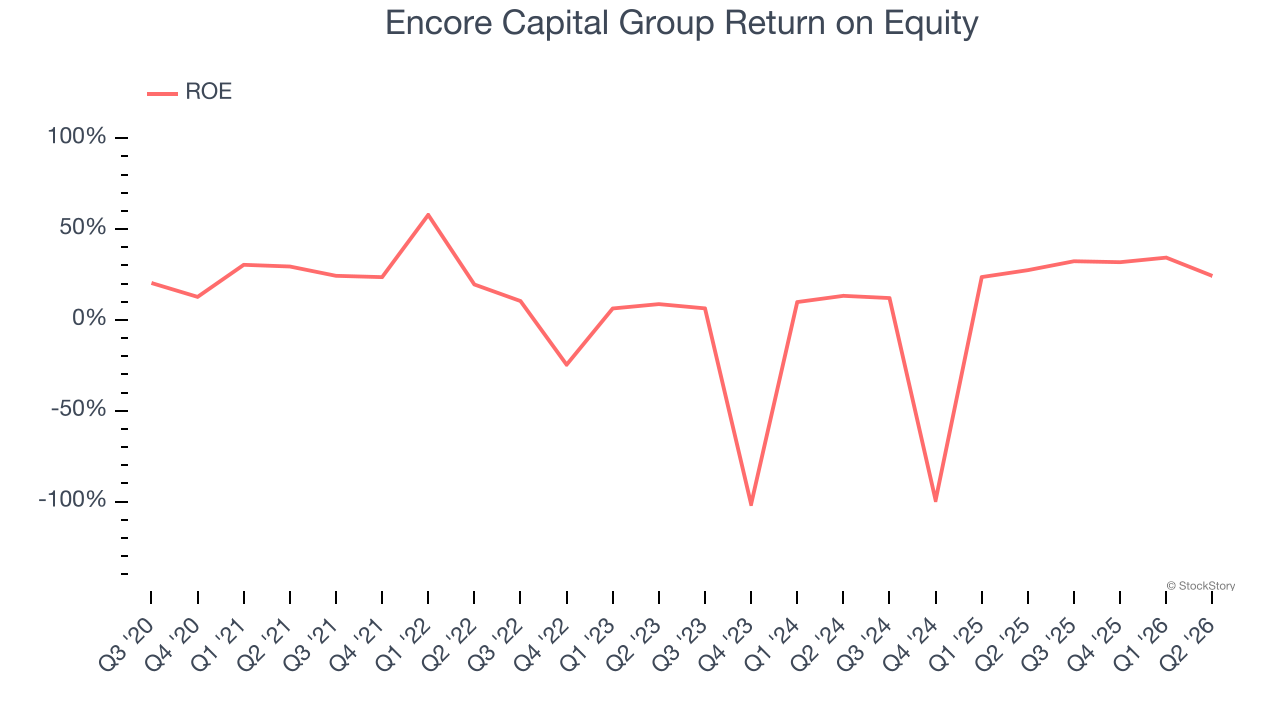
Return on equity (ROE) measures how effectively financial firms generate profit from each dollar of shareholder equity — a critical funding source. High-ROE institutions typically compound shareholder wealth faster over time through retained earnings, share repurchases, and dividend payments.
Over the last five years, Encore Capital Group has averaged an ROE of 7%, uninspiring for a company operating in a sector where the average shakes out around 10%.
3. High Debt Levels Increase Risk
Encore Capital Group reported $182.9 million of cash and $4.18 billion of debt on its balance sheet in the most recent quarter.
As investors in high-quality companies, we primarily focus on whether a company’s profits can support its debt.
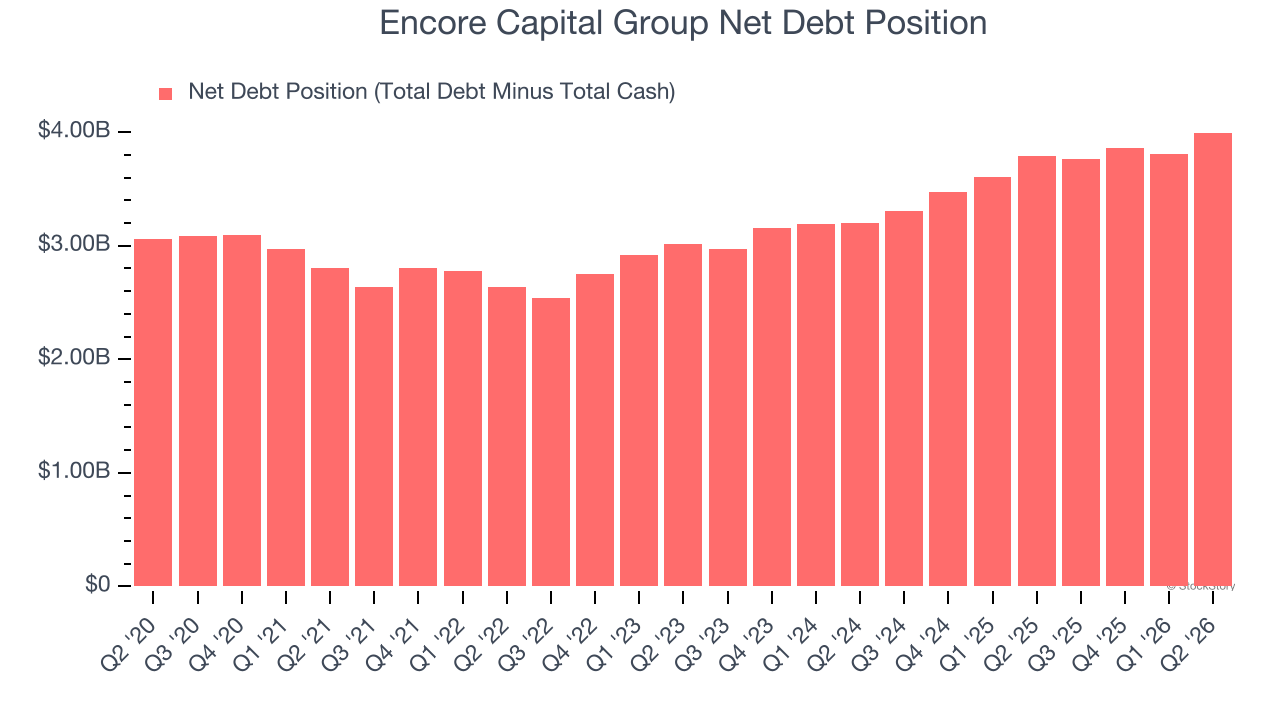
With $745.5 million of EBITDA over the last 12 months, we view Encore Capital Group’s 5.4× net-debt-to-EBITDA ratio as inadequate. The company’s lacking profits relative to its borrowings give it little breathing room, raising red flags.
Final Judgment
Encore Capital Group isn’t a terrible business, but it isn’t one of our picks. With its shares outperforming the market lately, the stock trades at 1.7× forward P/B (or $95.89 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward one of Charlie Munger’s all-time favorite businesses.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.