
Let’s dig into the relative performance of Tractor Supply (NASDAQ:TSCO) and its peers as we unravel the now-completed Q2 consumer retail earnings season.
Consumer retail companies operate the brick-and-mortar stores where consumers have shopped for centuries. The way people shop is changing with increased penetration of technology, but these retailers are adapting and still very much a part of the consumer fabric.
The 54 consumer retail stocks we track reported a satisfactory Q2. As a group, revenues were in line with analysts’ consensus estimates while next quarter’s revenue guidance was 0.6% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 5.7% since the latest earnings results.
Tractor Supply (NASDAQ:TSCO)
Started as a mail-order tractor parts business, Tractor Supply (NASDAQ:TSCO) is a retailer of general goods such as agricultural supplies, hardware, and pet food for the rural consumer.
Tractor Supply reported revenues of $4.54 billion, up 2.3% year on year. This print fell short of analysts’ expectations by 1.1%. Overall, it was a softer quarter for the company with full-year EPS guidance missing analysts’ expectations significantly and a significant miss of analysts’ EPS estimates.
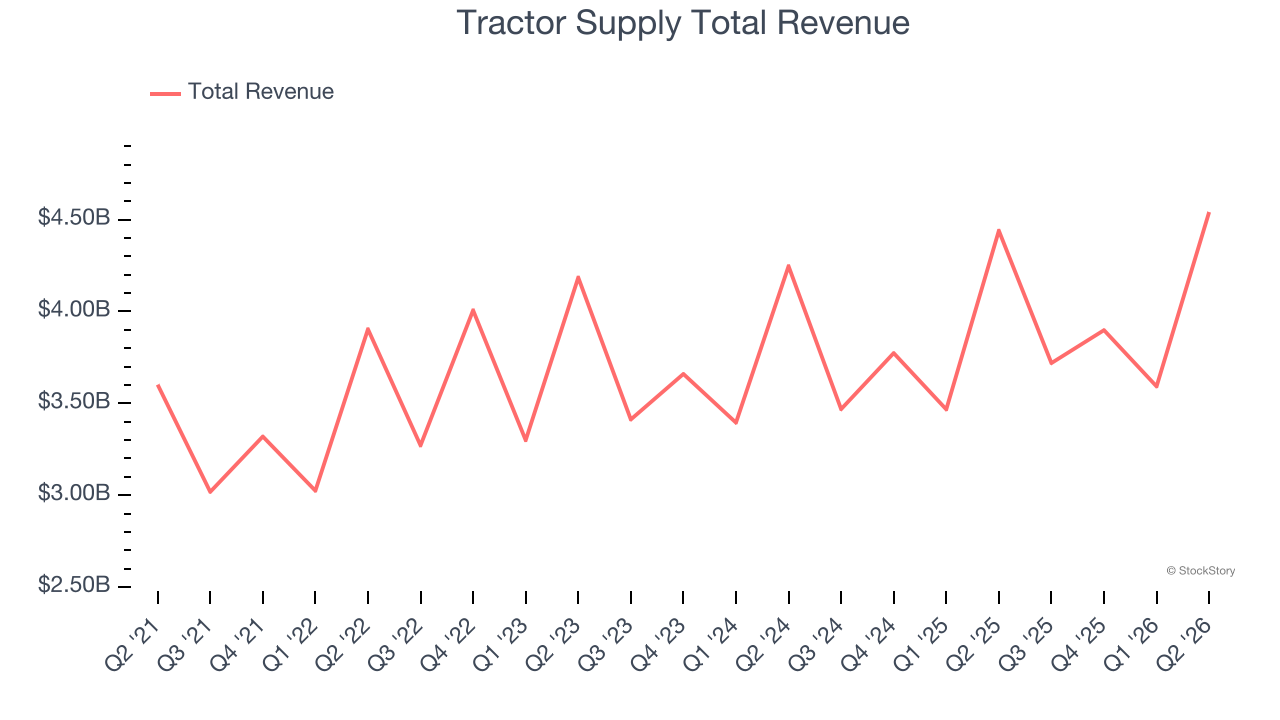
Interestingly, the stock is up 6.8% since reporting and currently trades at $31.37.
Read our full report on Tractor Supply here, it’s free.
Best Q2: Tilly's (NYSE:TLYS)
With an emphasis on skate and surf culture, Tilly’s (NYSE:TLYS) is a specialty retailer that sells clothing, footwear, and accessories geared towards fashion-forward teens and young adults.
Tilly's reported revenues of $163.5 million, up 8.1% year on year, outperforming analysts’ expectations by 4.1%. The business had an incredible quarter with EPS guidance for next quarter exceeding analysts’ expectations and a beat of analysts’ EPS estimates.
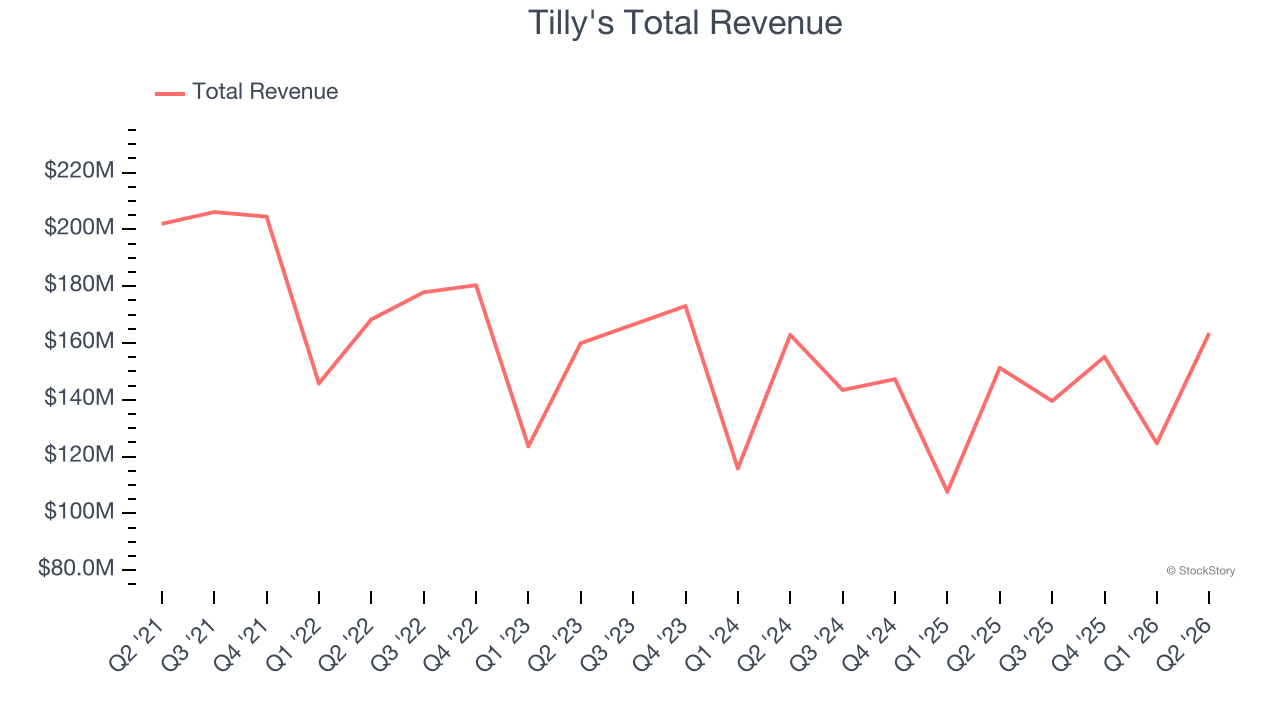
Tilly's pulled off the highest guidance raise among its peers. The market seems happy with the results as the stock is up 20.7% since reporting. It currently trades at $4.60.
Is now the time to buy Tilly's? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: America's Car-Mart (NASDAQ:CRMT)
With a strong presence in the Southern and Central US, America’s Car-Mart (NASDAQ:CRMT) sells used cars to budget-conscious consumers.
America's Car-Mart reported revenues of $144.2 million, down 57.6% year on year, falling short of analysts’ expectations by 36%. It was a disappointing quarter as it posted a significant miss of analysts’ EPS estimates.
America's Car-Mart delivered the weakest performance against analyst estimates and slowest revenue growth of the whole group. As expected, the stock is down 58.2% since the results and currently trades at $1.04.
Read our full analysis of America's Car-Mart’s results here.
Boot Barn (NYSE:BOOT)
With a strong store presence in Texas, California, Florida, and Oklahoma, Boot Barn (NYSE:BOOT) is a western-inspired apparel and footwear retailer.
Boot Barn reported revenues of $593.5 million, up 17.7% year on year. This number beat analysts’ expectations by 1.7%. More broadly, it was a satisfactory quarter as it also produced a beat of analysts’ EPS estimates but EPS guidance for next quarter missing analysts’ expectations significantly.
The stock is down 19.1% since reporting and currently trades at $122.04.
Read our full, actionable report on Boot Barn here, it’s free.
MarineMax (NYSE:HZO)
Appropriately headquartered in Clearwater, Florida, MarineMax (NYSE:HZO) sells boats, yachts, and other marine products.
MarineMax reported revenues of $611.3 million, down 7% year on year. This print lagged analysts’ expectations by 10.8%. Overall, it was a slower quarter as it also logged a slight miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
The stock is up 58.5% since reporting and currently trades at $52.18.
Read our full, actionable report on MarineMax here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.