
Barrett has been treading water for the past six months, recording a small return of 2.3% while holding steady at $30.51. The stock also fell short of the S&P 500’s 15.9% gain during that period.
Is there a buying opportunity in Barrett, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Barrett Not Exciting?
We don’t have much confidence in Barrett. Here are three reasons we avoid BBSI, plus one stock we’d rather own.
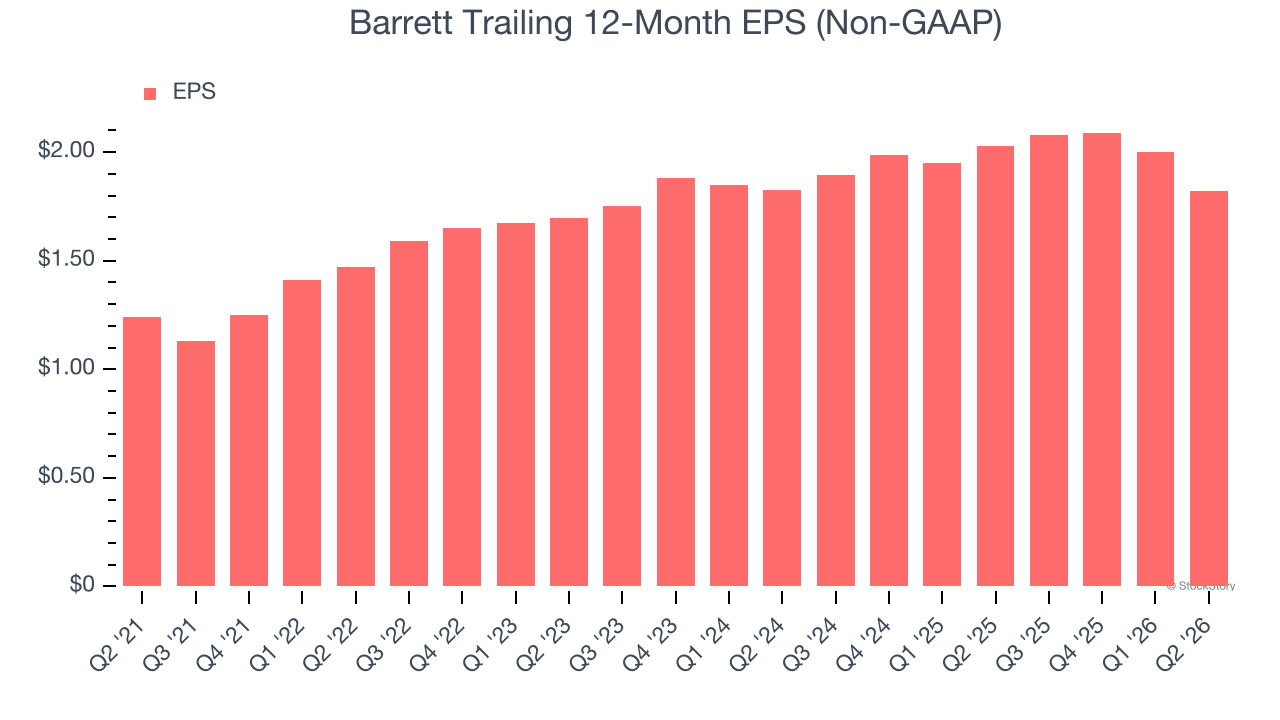
1. EPS Growth Has Stalled Over the Last Two Years
While long-term earnings trends give us the big picture, we also track EPS over a shorter period because it can provide insight into an emerging theme or development for the business.
Barrett’s flat EPS over the last two years was worse than its 7.5% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
2. Breakeven Free Cash Flow Limits Reinvestment Potential
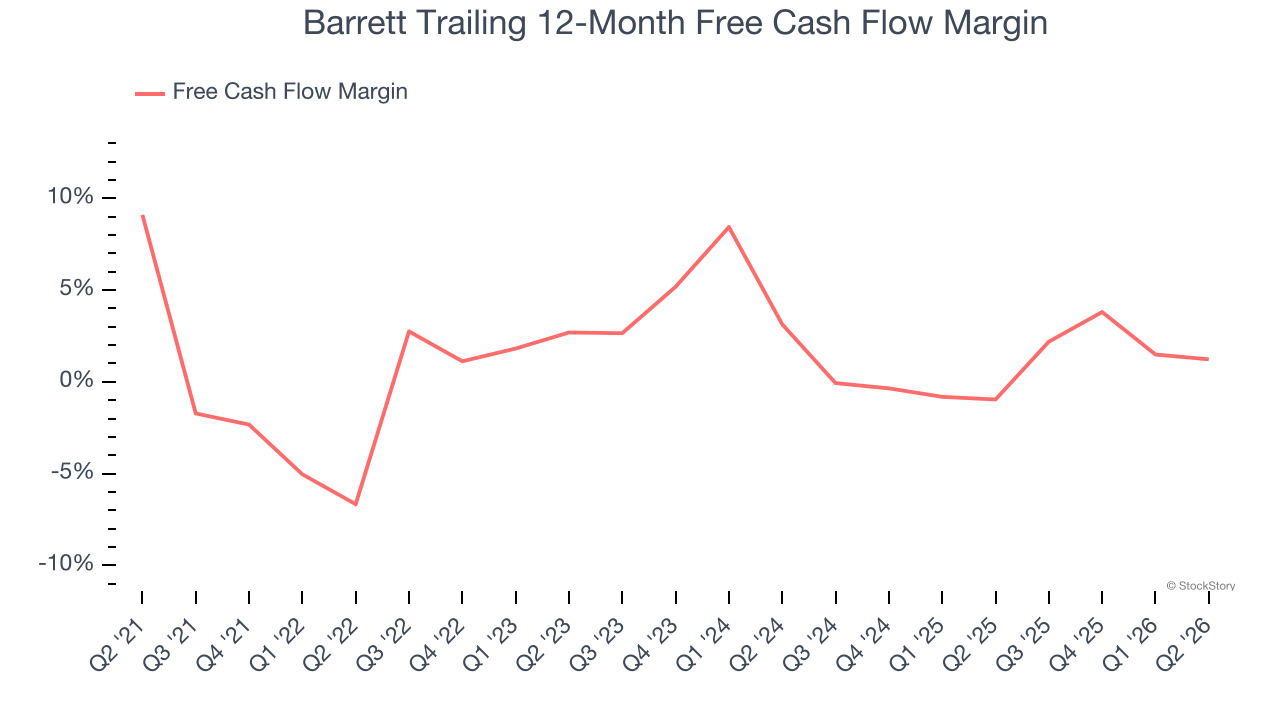
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Barrett broke even from a free cash flow perspective over the last five years, giving the company limited opportunities to return capital to shareholders.
3. New Investments Fail to Bear Fruit as ROIC Declines
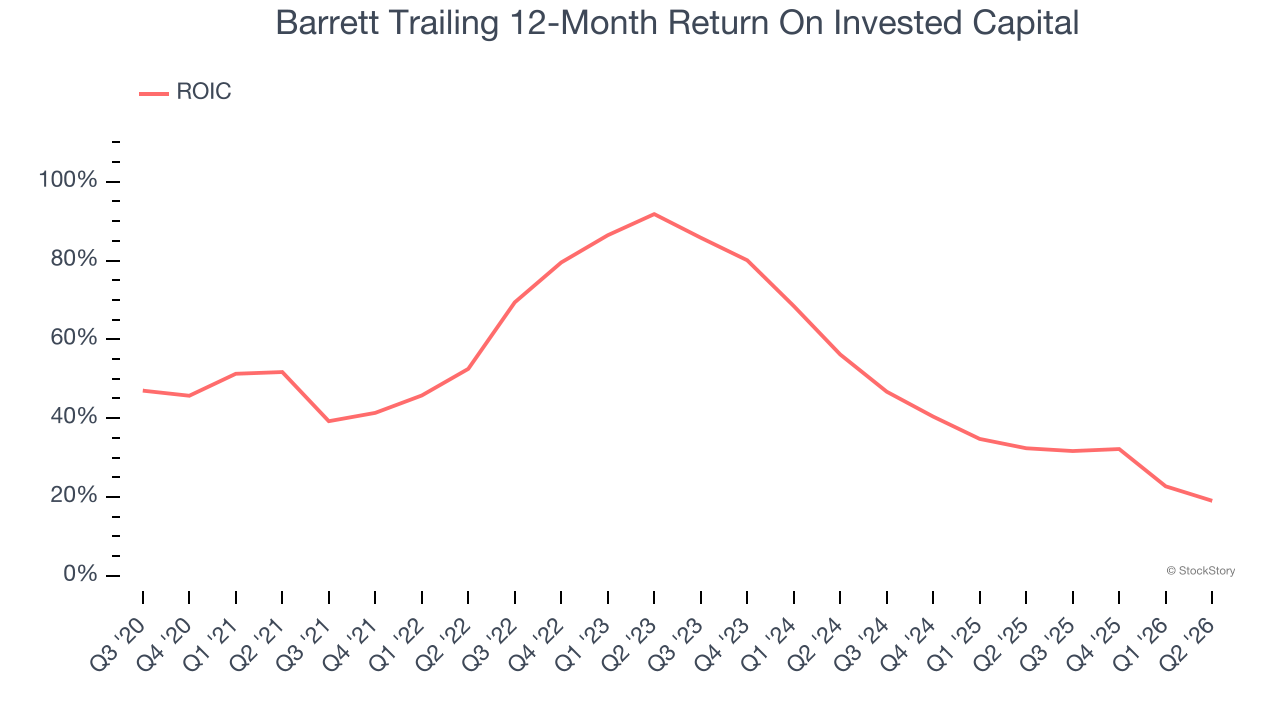
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Barrett’s ROIC has unfortunately decreased significantly. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Barrett isn’t a terrible business, but it isn’t one of our picks. With its shares underperforming the market lately, the stock trades at $30.51 per share (or a forward price-to-sales ratio of 0.6×). The market typically values companies like Barrett based on their anticipated profits for the next 12 months, but there aren’t enough published estimates to arrive at a reliable number. You should avoid this stock for now - better opportunities lie elsewhere. We’d recommend looking at one of our top digital advertising picks.
Stocks We Like More Than Barrett
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.