
Over the last six months, Kyndryl’s shares have sunk to $11.55, producing a disappointing 10.5% loss - a stark contrast to the S&P 500’s 15.9% gain. This might have investors contemplating their next move.
Is there a buying opportunity in Kyndryl, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Kyndryl Not Exciting?
Even though the stock has become cheaper, we don’t have much confidence in Kyndryl. Here are three reasons why KD doesn’t excite us, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
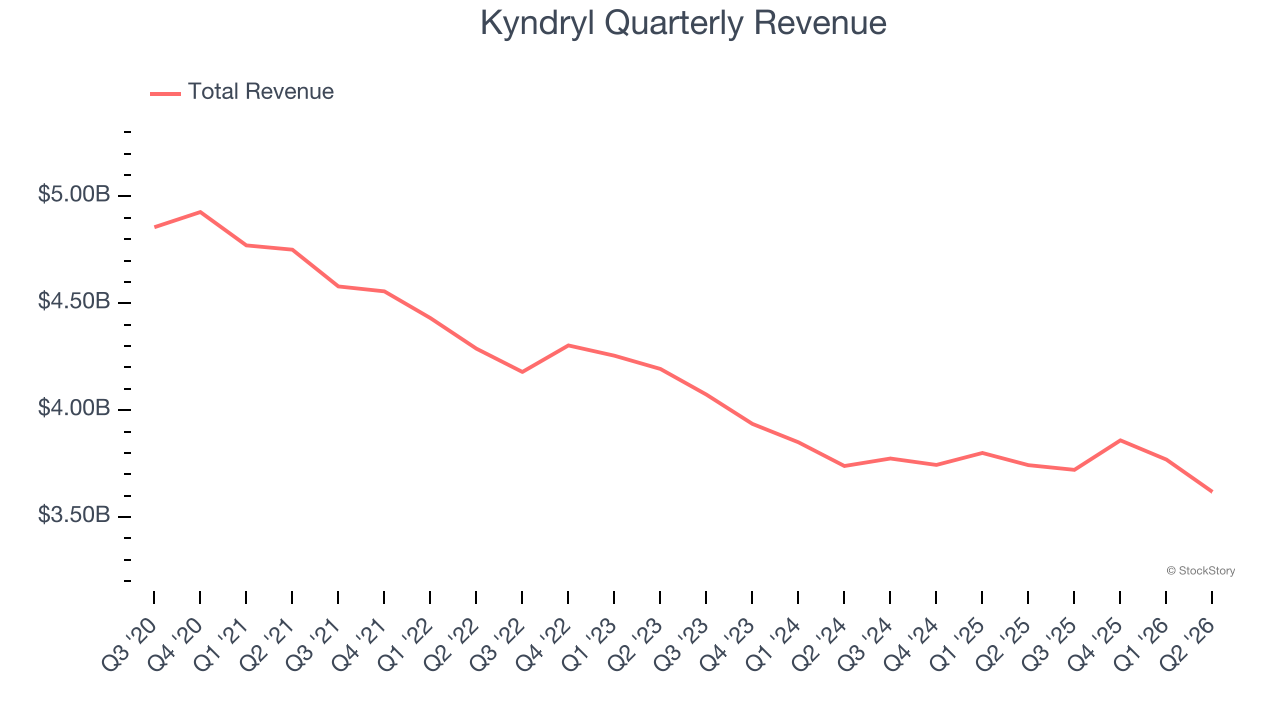
A company’s long-term sales performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Kyndryl’s demand was weak over the last five years as its sales fell at a 5% annual rate. This was below our standards and is a sign of lacking business quality.
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Kyndryl’s revenue to drop by 1%, close to its 5% annualized declines for the past five years. This projection is underwhelming and suggests its newer products and services will not accelerate its top-line performance yet.
3. Previous Growth Initiatives Have Lost Money
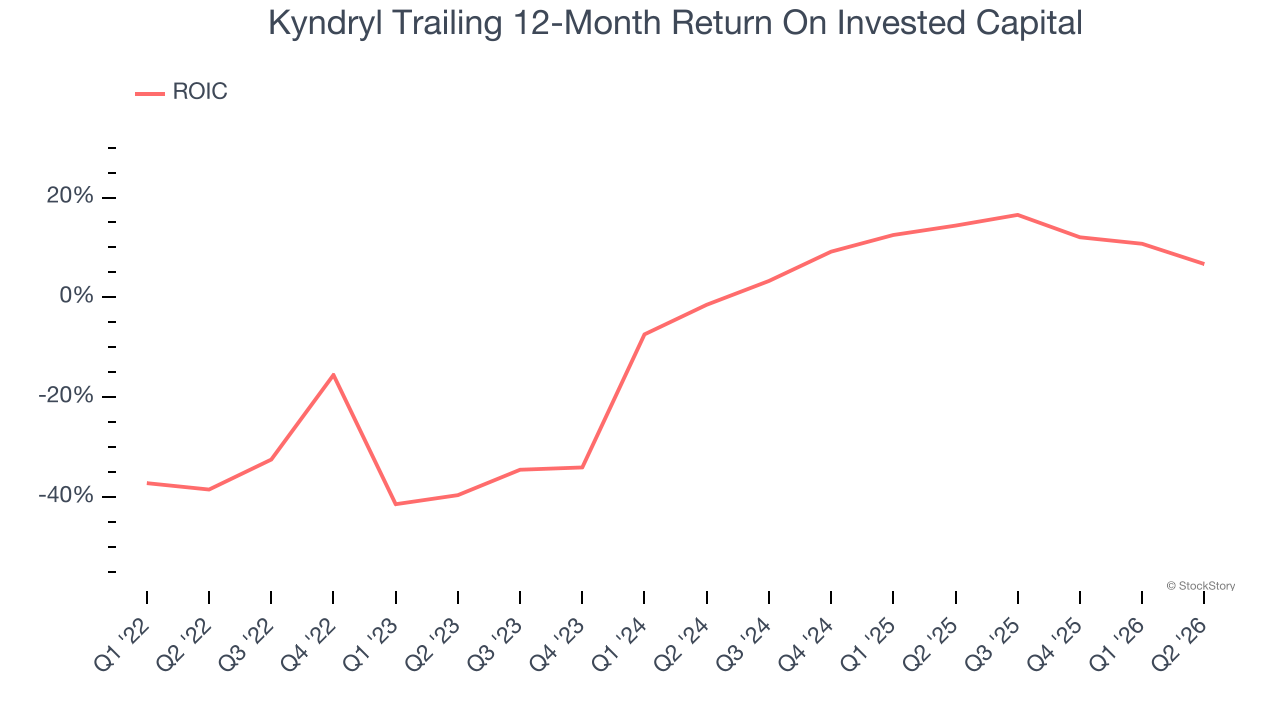
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Kyndryl’s five-year average ROIC was negative 11.7%, meaning management lost money while trying to expand the business. Its returns were among the worst in the business services sector.
Final Judgment
Kyndryl isn’t a terrible business, but it doesn’t pass our bar. After the recent drawdown, the stock trades at 4.9× forward P/E (or $11.55 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better investments elsewhere. Let us point you toward one of our top software and edge computing picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.