

C3.ai has had an impressive run over the past six months as its shares have beaten the S&P 500 by 9.4%. The stock now trades at $11.00, marking a 25.4% gain. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in C3.ai, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think C3.ai Will Underperform?
We’re glad investors have benefited from the price increase, but we’re sitting this one out for now. Here are three reasons why there are better opportunities than AI, plus one stock we’d rather own.
1. Declining Billings Reflect Product and Sales Weakness
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
C3.ai’s billings came in at $69.63 million in Q2, and it averaged 24.5% year-on-year declines over the last four quarters. This performance was underwhelming and shows the company faced challenges in acquiring and retaining customers. It also suggests there may be increasing competition or market saturation. 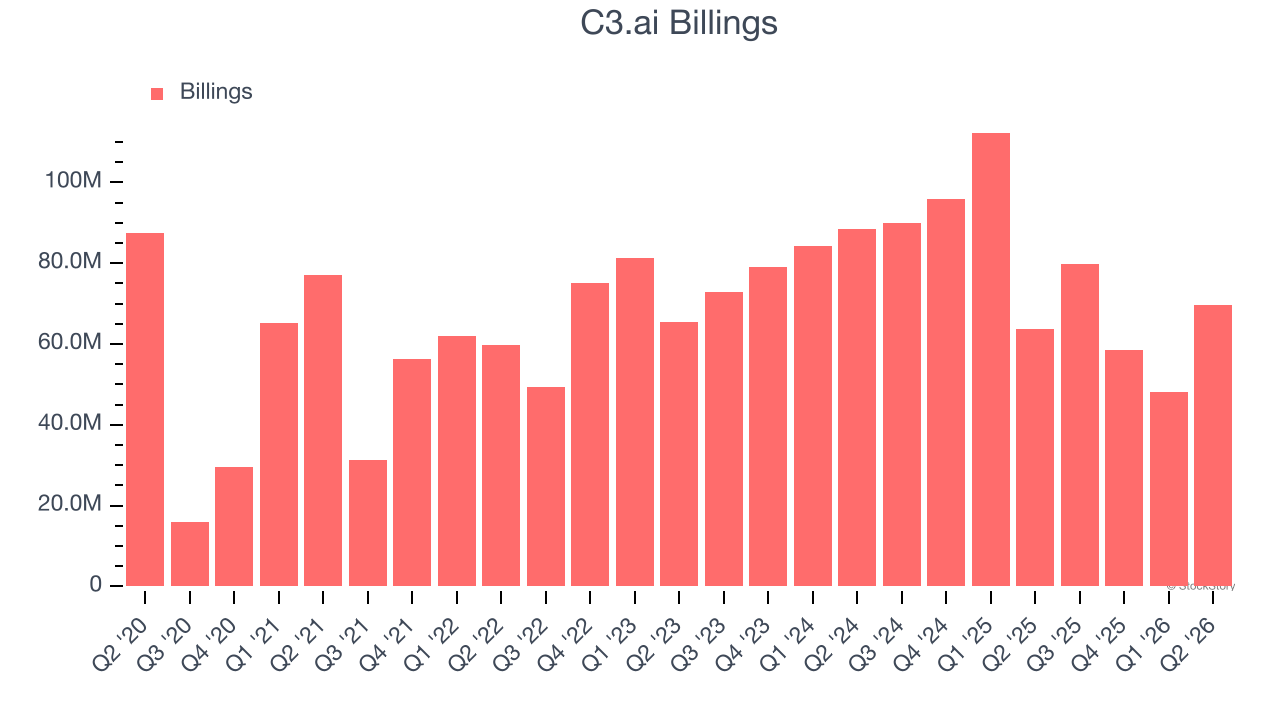
2. Low Gross Margin Reveals Weak Structural Profitability
For software companies like C3.ai, gross profit tells us how much money remains after paying for the base cost of products and services (typically servers, licenses, and certain personnel). These costs are usually low as a percentage of revenue, explaining why software is more lucrative than other sectors.
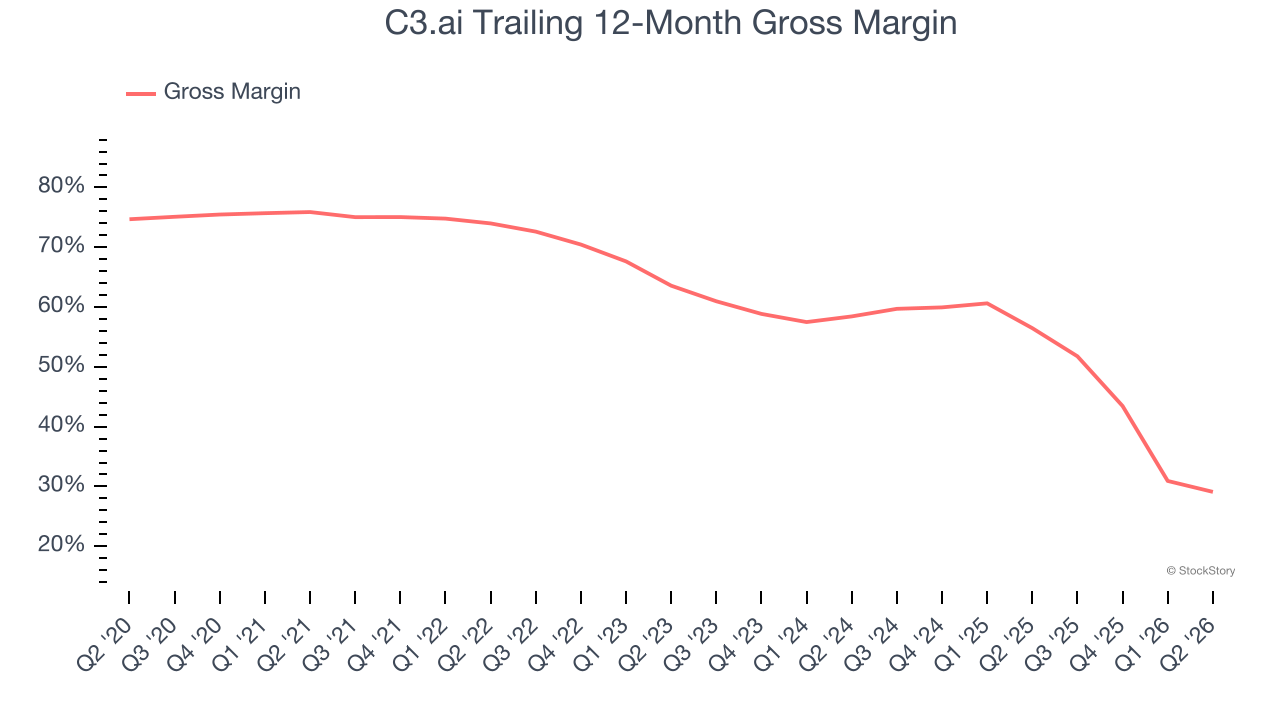
C3.ai’s gross margin is substantially worse than most software businesses, signaling it has relatively high infrastructure costs compared to asset-lite businesses like ServiceNow. As you can see below, it averaged a 29.1% gross margin over the last year. That means C3.ai paid its providers a lot of money ($70.91 for every $100 in revenue) to run its business.
The market not only cares about gross margin levels but also how they change over time because expansion creates firepower for profitability and free cash generation. C3.ai has seen gross margins decline by 29.3 percentage points over the last 2 years, which is among the worst in the software space.
3. Cash Burn Ignites Concerns
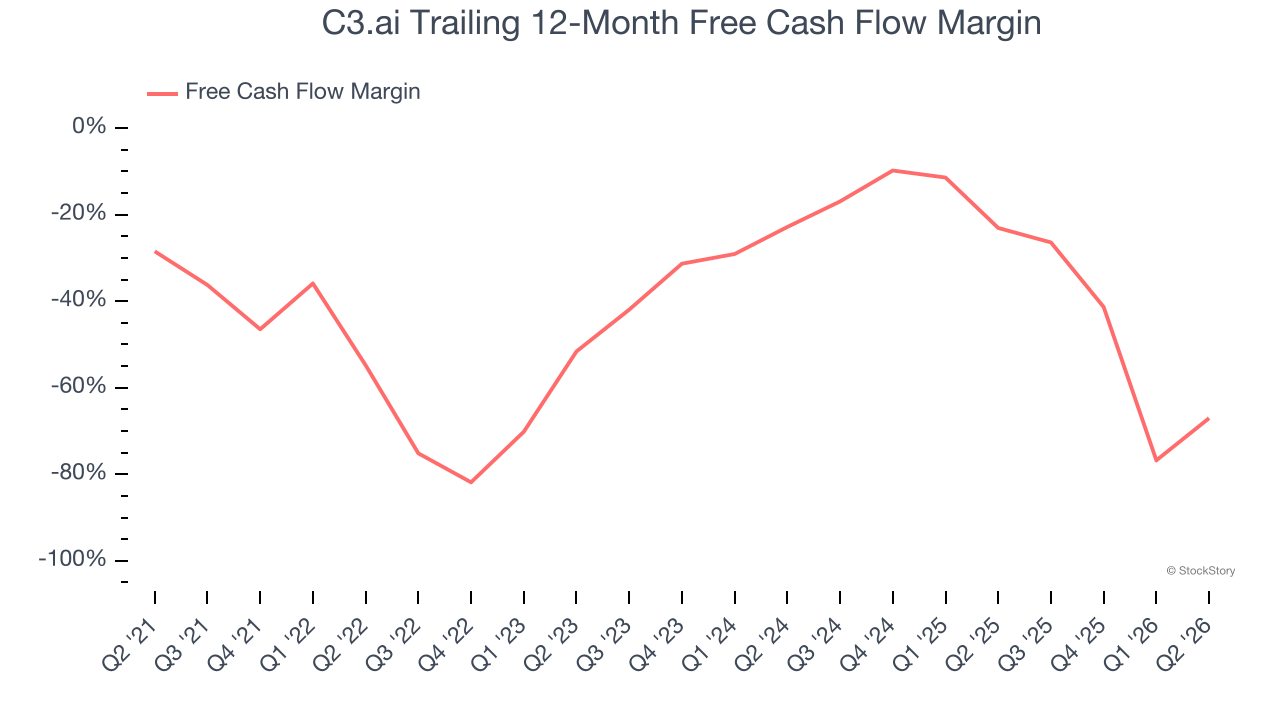
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
While C3.ai posted positive free cash flow this quarter, the broader story hasn’t been so clean. C3.ai’s demanding reinvestments have drained its resources over the last year, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 67%, meaning it lit $67.03 of cash on fire for every $100 in revenue.
Final Judgment
We cheer for all companies solving complex business issues, but in the case of C3.ai, we’ll be cheering from the sidelines. With its shares topping the market in recent months, the stock trades at 7.6× forward price-to-sales (or $11.00 per share). This valuation tells us a lot of optimism is priced in - we think there are better stocks to buy right now. We’d recommend looking at the Amazon and PayPal of Latin America.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.